Statistics drawn from the CV VC Crypto Valley Top 50 & Ecosystem Report published in April 2026, covering year-end 2025 data.
The number that travels the farthest is 1,766.
That is how many active blockchain companies the Crypto Valley ecosystem — Switzerland and Liechtenstein combined — contained as of the most recent CV VC count. The figure circulates in press releases, conference keynotes, and business development pitches from Zurich to Singapore. It is accurate. It is also, like most large round-ish numbers attached to a place’s identity, only a partial picture.
This is a field note on what that picture actually looks like — the geography behind the statistic, what the funding numbers reveal when you look past the headline, and where the gap is between the brochure and the place.
The Number Behind the Headline: 1,766 and What It Actually Means
Start with the context that rarely makes the summary slides.
1,766 active blockchain companies at the end of 2025, up 1% year-on-year, and up 134% since 2020. The compound annual growth rate from 2020 to 2024 sat at 18.8% — that was not startup-hype growth, that was sustained institutional expansion. The kind of growth that requires lawyers registering companies, accountants filing accounts, offices paying rent. What 2025 added was a new all-time high and almost no net movement: the curve has flattened out at the top.
But “active blockchain company” is a wide category. It includes the infrastructure layer (about 20% of the total), financial services firms (18%), consulting and advisory outfits (17%), and a long tail of security, audit, GameFi, NFT, DeFi, software development, and exchange businesses. The ecosystem is diverse in a way that matters: this is not a monoculture built on one protocol or one founder circle. It has redundancy.
The valuation figure for the Top 50 alone — $467 billion as of April 2026 — is the number that tells you something different. It tells you that a very small number of companies hold a very large share of the value. Sixteen of the top 25 blockchain platforms by valuation are headquartered in Zug. Those sixteen account for 97% of the total Top 50 valuation. The broader 1,766 is the whole population. The value concentration is a different story.
Zug’s Monopoly: 40% of Companies, 88% of the Capital
The headline says “Crypto Valley.” The footnote says “Zug.”
Of the 1,766 companies, 715 — 40% — are registered in the canton of Zug. Zurich follows with 257 (15%). Then comes a significant drop: Ticino with 119, Geneva with 87, Lucerne with 73, Liechtenstein with 72, and Vaud with 56.
But the incorporation share only tells part of the story. What is more striking is the capital concentration. In 2025, Zug absorbed 88% of all disclosed blockchain investment within Swiss borders.
Two reasons explain this. First, the largest companies — Sygnum Bank ($58M round in 2025), the TON ecosystem presence, the infrastructure layer firms — are based in Zug. Second, the “Crypto Valley” brand itself creates a network effect in capital: Zug is a short train ride from Zurich, so an investor visiting Switzerland can meet several companies in a single day. The brand concentrates attention, which concentrates capital, which concentrates company formation.
What makes Zug’s new incorporation rate particularly telling: its share of new registrations jumped from 35% in 2020 to 49% in 2024. Founders who might once have registered in Zurich for the talent pool, or Geneva for the international finance connections, are increasingly choosing Zug from the start. The regulatory predictability matters. So does the cluster effect — if your lawyers, your auditors, your potential co-founders, and your first investors all have Zug addresses, friction is lower there than anywhere else in Switzerland.
$728M and the Shape of the Money
Switzerland raised $728 million across 31 blockchain deals in 2025. That is a 37% jump from 2024, in a year when global blockchain funding grew 30% on aggregate but deal count fell sharply.
The deal count matters. Thirty-one transactions for $728 million means an average of roughly $23.5 million per deal. That is not seed money. That is Series A and B capital going into companies with established business models, regulatory licenses, and real revenue — or credible paths to it.
| Metric | Figure |
|---|---|
| Total raised | $728M |
| Deal count | 31 |
| Year-on-year increase | +37% |
| Share of European blockchain VC | 47% |
| Share of global blockchain funding | 5% |
| Largest single deal | $400M (TON) |
| Second largest | $58M (Sygnum Bank) |
The $400M TON deal is an outlier that inflates the average. Strip it out, and 30 deals raised $328 million — still $10.9 million per deal. Still institutional-scale capital, not angels backing whitepapers.
Switzerland’s 47% share of European blockchain venture funding is the statistic that has attracted the most external commentary in 2026. The framing — “Switzerland dominates European crypto VC” — is accurate but slightly misleading. What it reflects is not that Switzerland has become more attractive relative to its historical position. It is that London post-Brexit, Berlin in economic contraction, and Paris facing regulatory ambiguity have all become less reliable as crypto capital destinations. Switzerland’s share is partly absolute growth, partly relative to competitors weakening.
What “Crypto Valley” Looks Like Beyond the Report
Here is where institutional reports and field notes diverge.
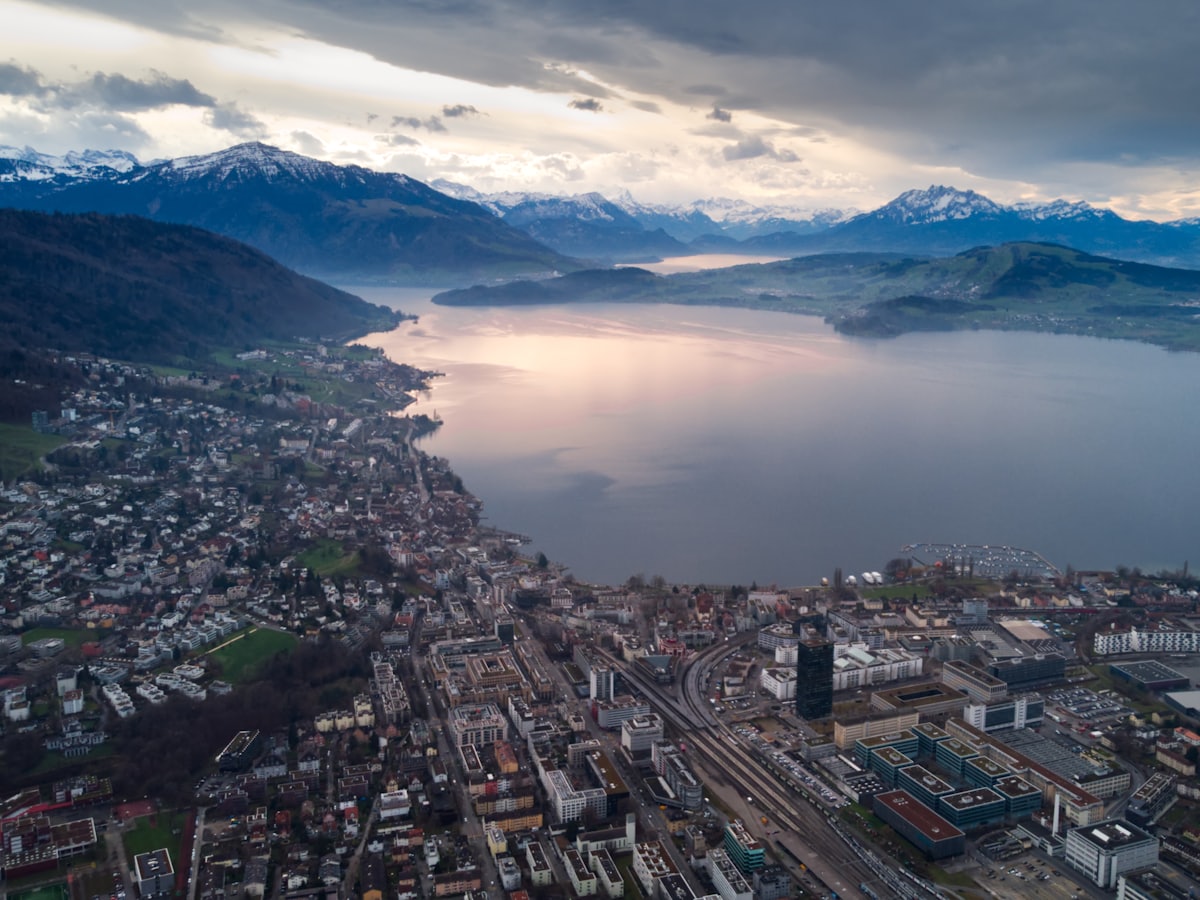
Zug is a small Swiss city of about 30,000 residents. Its old town is well-preserved, its lake is beautiful by any standard, and its tax rates remain among the lowest in Switzerland. These things are all true and all widely reported.
What the reports do not convey is how compact it is. A large share of the ecosystem’s addresses — CV Labs, the foundations, the banks, the law firms — sits on the same six streets in Zug, which is its own field note on the physical geography of the ecosystem, mapped from published company addresses.
The lake is genuinely expensive, incidentally. The canton’s tax advantages attract wealth that then bids up real estate: Zuger Kantonalbank puts a typical 3- to 3.5-room flat in Zug at around CHF 2,600 a month, more than CHF 4,000 at the high end, with rents up 4.5% year on year in mid-2025 against 3% nationally (Zuger KB via zug4you.ch, October 2025). If you are weighing a move from Berlin or Singapore on the assumption that the tax savings offset living costs, run that rent number first. It works as a form of selection pressure: the people who need to be in Zug are the ones who can afford to be in Zug.
What the 1,766 number does not tell you is how many of those companies have a physical office in Switzerland versus a registered address and a team in Berlin, Lisbon, or Singapore. The CV VC report tracks registrations. Presence is a different variable. Both are real — the legal entity matters, the regulatory address matters — but the company count is not a headcount of people working in Zug, and the report does not claim to be one.
The Other Cities Nobody Talks About
Zurich gets mentioned as the second city (257 companies, 15% of the total). Beyond that, most coverage stops. The regional specializations further down the list are more interesting.
Geneva — 87 companies, 5% of the total — has developed a concentration in Security, Audit & Compliance. Forty percent of Geneva’s blockchain firms operate in this sub-sector. This tracks with Geneva’s existing financial industry: private banking, family offices, and institutional asset management all have compliance-heavy operations in the city, and the crypto firms that serve them have clustered there rather than making the journey to Zug.
Lucerne is quietly becoming notable for DeFi. The city hosts over 10% of Switzerland’s DeFi sector — a disproportionate share for a city with only 73 total blockchain companies. This is the kind of regional specialization that does not fit neatly into a press release but tells you something about where specific communities of practice are forming.
Ticino (119 companies, up 15.5% in 2025 — the fastest-growing canton in the latest report) benefits from proximity to Italy and a different linguistic and professional culture. It is not a major capital magnet yet, but the company count has grown consistently.
Liechtenstein’s 72 firms punch above their weight because of the Token Act — the principality’s 2019 blockchain legislation, which created a legal framework for tokenized assets that predated most European regulatory clarity. Firms that need specific token law treatment sometimes incorporate in Liechtenstein rather than Zug.
| Region | Companies | Share | Notable specialization |
|---|---|---|---|
| Zug | 715 | 40% | Capital markets, infrastructure, financial services |
| Zurich | 257 | 15% | Tech talent, exchange listings |
| Ticino | 119 | 7% | Italy proximity, cross-border activity |
| Geneva | 87 | 5% | Security, audit & compliance |
| Lucerne | 73 | 4% | DeFi concentration |
| Liechtenstein | 72 | 4% | Token Act, tokenized assets |
| Vaud | 56 | 3% | — |
CV Labs and What the Co-working Scene Actually Tells You
CV Labs — the incubator associated with CV VC — hosts 197 blockchain companies, roughly 11% of the broader ecosystem. In 2024, CV Labs saw 38 new company incorporations, up 124% year-on-year.
That 124% jump in a single year is worth pausing on. It is not just organic growth. It reflects the point at which the physical infrastructure of an ecosystem starts attracting founders who would otherwise not have come. When the incubator has a track record, a network of mentors, access to the VC fund’s deal flow, and physical adjacency to the other companies you want to know — the decision to incorporate at that address rather than elsewhere becomes easier. CV Labs is now large enough to create its own gravity.
The co-working scene in Zug is concentrated: CV Labs alone hosts roughly one in nine of the ecosystem’s companies at a single address. That is characteristic of small-city ecosystems — more contact per square kilometre than in a dispersed metropolis, which can mean faster information flow and less privacy at the same time. Whether this is an advantage depends on what you are trying to do.
What the 2026 Crypto Valley Conference Signals
The Crypto Valley Conference 2026 ran on 28 May in Rotkreuz — close enough to Zug to be in the same gravity field. The published programme packed 47 sessions, among them 14 keynotes, 14 panels, eight workshops and four roundtables, across three stages into a single day, listed more than a hundred speakers, and closed with a sunset boat cruise on Lake Zug.
The programme’s own framing was instructive. Its five published focus areas were on-chain markets, cybersecurity and privacy, blockchain’s foundational technology layer, crypto regulation and compliance, and the race with AI and quantum technologies — infrastructure and compliance, not protocol launches or NFT cycles. The public-sector names on the speaker list point the same way: the deputy head of MROS, Switzerland’s money-laundering reporting office, sat on a cross-border crypto compliance roundtable, and Heinz Tännler, Zug’s cantonal finance director, gave a keynote.
That line-up is not incidental. It reflects a maturation in the relationship between Swiss public authorities and the blockchain layer. FINMA’s January 2026 custody guidance is part of the same arc — the regulatory perimeter is being drawn more precisely, not because the regulator is becoming more hostile, but because the industry is large enough to require it.
The conference’s boat cruise closing on Lake Zug is a detail that gets included in every description of the event and is usually treated as color. The official schedule treats it as more than that: the organisers list the sunset cruise as a signature CVC tradition, running from 18:30 to 21:00, and it is the evening slot with no talks attached. The formal programme is where the ideas get presented; the cruise is the time the schedule leaves for conversation. Zug’s geography — the lake, the compact old town, the easy train connections — is not incidental to how the ecosystem functions. It is infrastructure of a different kind.
The Crypto Valley Conference is not the only event worth the train ticket if you live near Zug, but it is the one most worth clearing the calendar for. For the full Swiss-orbit shortlist — the Web3 Banking Symposium, Point Zero Forum, and the international names you can safely skip — see the separate field note on which crypto conferences actually matter from Zug in 2026.
The Gap Between the Brochure and the Reality
The Crypto Valley brochure version: 1,766 companies, 134% growth, $728M raised, 47% of European VC, ten unicorns, the world’s most crypto-friendly regulatory environment.
All of that is accurate.
The field note version: a small Swiss city with expensive rent, a concentrated co-working scene, a regulatory regime that is sophisticated but demanding, and a company register that includes both genuinely active businesses and legal entities attached to distributed teams that are physically located elsewhere.
The gap between those two versions is not a contradiction. It is just the difference between a statistic and a place. The ecosystem is real and substantive. The institutions — FINMA, the DLT Act framework, the banking infrastructure at Sygnum and SEBA — are world-class. The conference each May is worth attending if you are trying to understand where the European and global crypto regulatory conversation is heading.
What the brochure cannot tell you is whether Zug is the right place for a specific company or person right now. That depends on what you need from a jurisdiction: the legal framework, the talent, the investor proximity, the tax structure, the physical presence, or simply the address on the business card that signals to counterparties that you are part of this ecosystem.
The address is still expensive. The 1,766 companies are still there.
Sources for this field note: CV VC Top 50 & Ecosystem Report 2026 / Switzerland $728M funding data / DL News — Europe’s crypto capital analysis / Crypto Valley Conference 2026. Related reading: FINMA Guidance 01/2026 — what it means for custody.